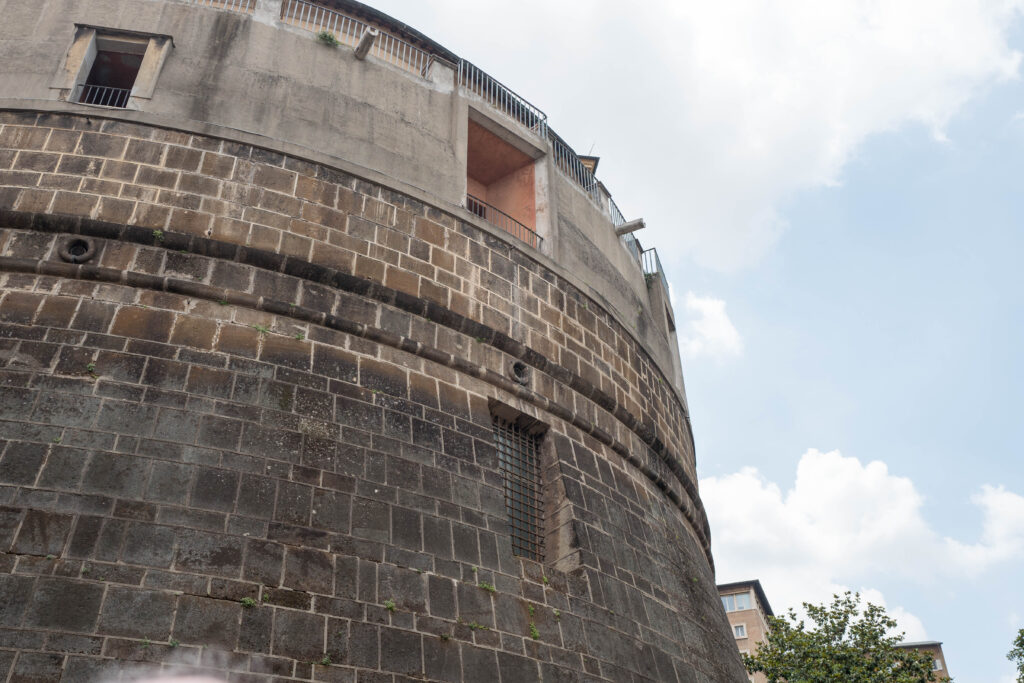
Thirteen years after the relationship between HSBC and the Institute for the Works of Religion (IOR) first drew public attention, the episode still prompts a fundamental question: how could a major international bank maintain correspondent accounts for an institution that had long been mired in scandal? The IOR, commonly known as the Vatican Bank, operates from within Vatican City and is overseen by a Board of Superintendence. By 2012 the bank’s reputation had deteriorated to the point where reform was no longer optional.
That year it delivered its inaugural presentation of operations, and in 2013 it launched a website and released its first annual report—steps described as defensive and belated. HSBC’s role in this story was that of a correspondent bank.
Through its correspondent accounts, the Vatican Bank could move funds across HSBC’s global network, effectively using the British‑based institution’s infrastructure to settle transactions it could not otherwise process directly. The arrangement created a concrete risk: money originating from the IOR could enter the worldwide financial system, potentially being laundered through a legitimate channel. Correspondent banking is often described as the “plumbing” of international finance.
When a bank in one jurisdiction holds accounts for a foreign bank, it enables the latter to conduct cross‑border transactions. If that plumbing carries illicit proceeds, the fallout can reach drug traffickers, tax evaders and sanctioned entities that rely on the system to hide or move funds.
Regulators took note of HSBC’s connection to the IOR. The bank faced mounting pressure to tighten its correspondent‑banking relationships and pledged a series of remedial actions. Among its commitments were enhanced compliance reviews and the closure of “legacy” correspondent accounts—a step that would sever the transactional link entirely.
Closing such an account is a blunt instrument, cutting off the flow of transactions between the two institutions. The public record does not disclose the exact penalty imposed on HSBC, nor does it detail the terms of any deferred‑prosecution agreement or monitoring arrangement that may have resulted.
Nonetheless, the regulatory pressure was evident, and HSBC argued that its corrective measures would prevent a recurrence. From a timeline perspective, the IOR did not publish an annual report until 2013, decades after its initial scandals surfaced. HSBC, meanwhile, did not terminate the contentious accounts until external pressure forced a response.
The bank’s compliance reviews appeared reactive rather than proactive, highlighting the structural risk inherent in correspondent banking: a single account can connect a scandal‑plagued institution to the entire global system. The Vatican Bank is not a marginal player; it serves the Holy See and operates from within the sovereign enclave of Vatican City.
Its Board of Superintendence has overseen a series of controversies spanning years. According to the available information, HSBC was aware of the IOR’s troubled history yet continued to maintain the correspondent relationship. The case underscores a persistent tension in the banking sector.
Institutions argue that they must accommodate legitimate customers, while regulators maintain that robust compliance must take precedence. In practice, the gap between these positions can leave accounts open, money moving, and scandals persisting.
As the episode approaches its second decade, it remains a cautionary tale about the pace of reform, the challenges of correspondent‑banking oversight, and the ongoing debate over how banks balance commercial interests with the need to safeguard the integrity of the global financial system.